News
7x24
Quotes
Economic Calendar
Video
Data
- Names
- Latest
- Prev.

Latest Update

Risk Warning on Trading HK Stocks
Despite Hong Kong's robust legal and regulatory framework, its stock market still faces unique risks and challenges, such as currency fluctuations due to the Hong Kong dollar's peg to the US dollar and the impact of mainland China's policy changes and economic conditions on Hong Kong stocks.

HK Stock Trading Fees and Taxation
Trading costs in the Hong Kong stock market include transaction fees, stamp duty, settlement charges, and currency conversion fees for foreign investors. Additionally, taxes may apply based on local regulations.

HK Non-Essential Consumer Goods Industry
The Hong Kong stock market encompasses non-essential consumption sectors like automotive, education, tourism, catering, and apparel. Of the 643 listed companies, 35% are mainland Chinese, making up 65% of the total market capitalization. Thus, it's heavily influenced by the Chinese economy.

HK Real Estate Industry
In recent years, the real estate and construction sector's share in the Hong Kong stock index has notably decreased. Nevertheless, as of 2022, it retains around 10% market share, covering real estate development, construction engineering, investment, and property management.
View All

No data


News
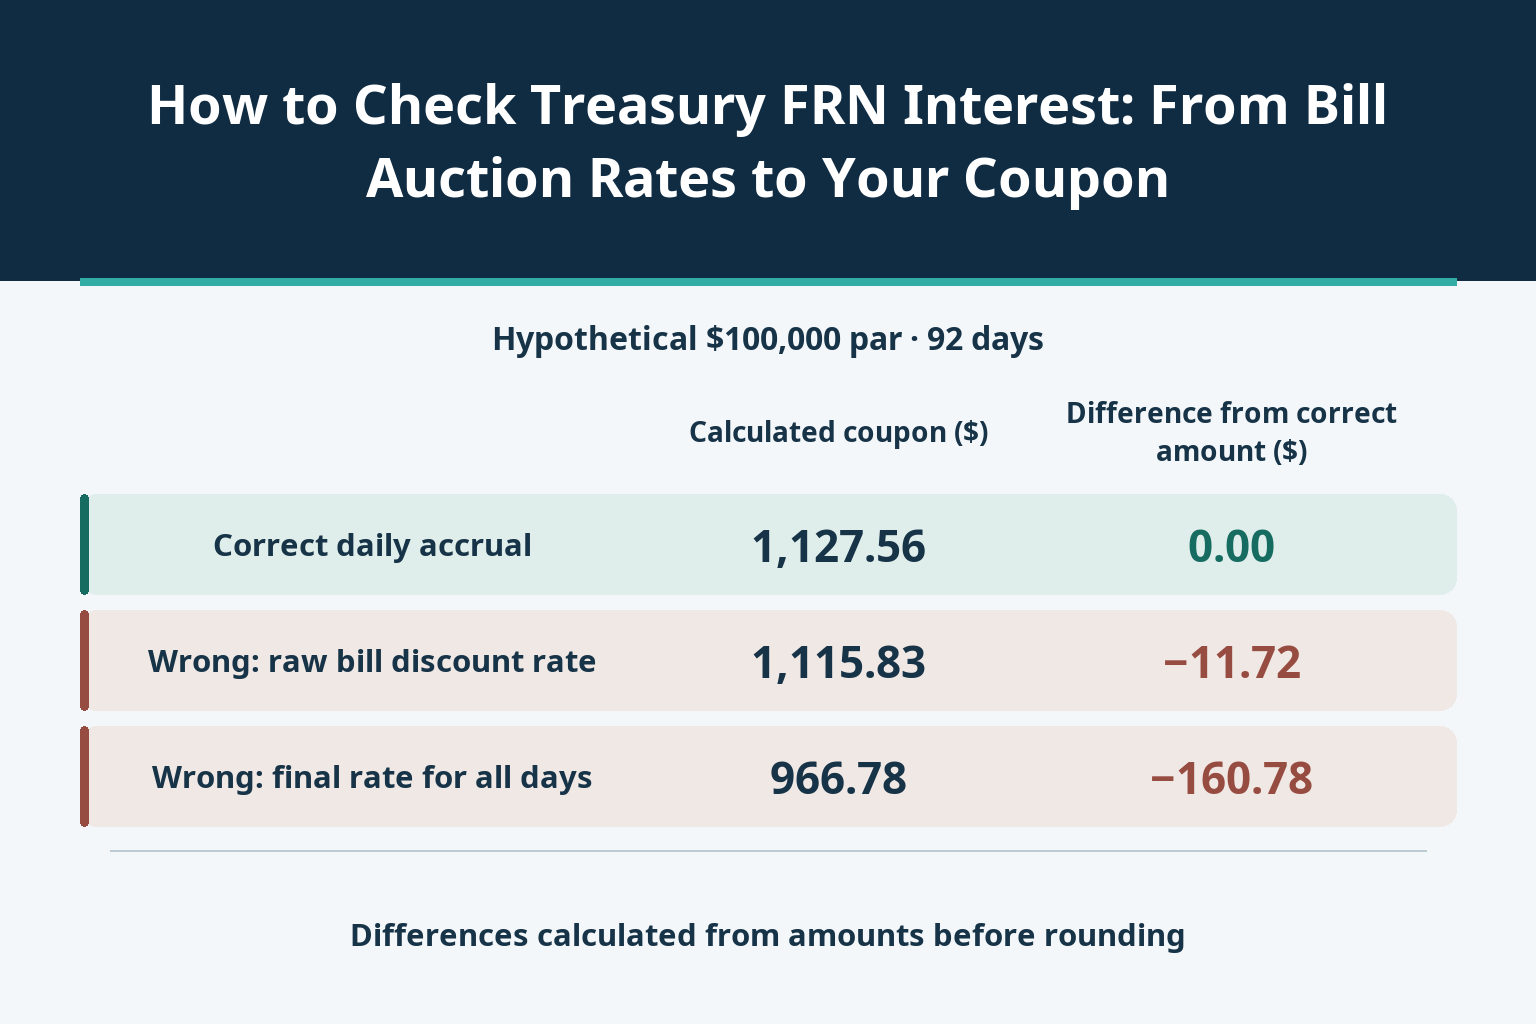
A Treasury FRN coupon is a sum of daily accruals, not the latest bill rate multiplied by a quarter. A $100,000 example separates rate conversion, reset timing, the payment lockout and interest paid when buying between coupon dates.
zhan chen
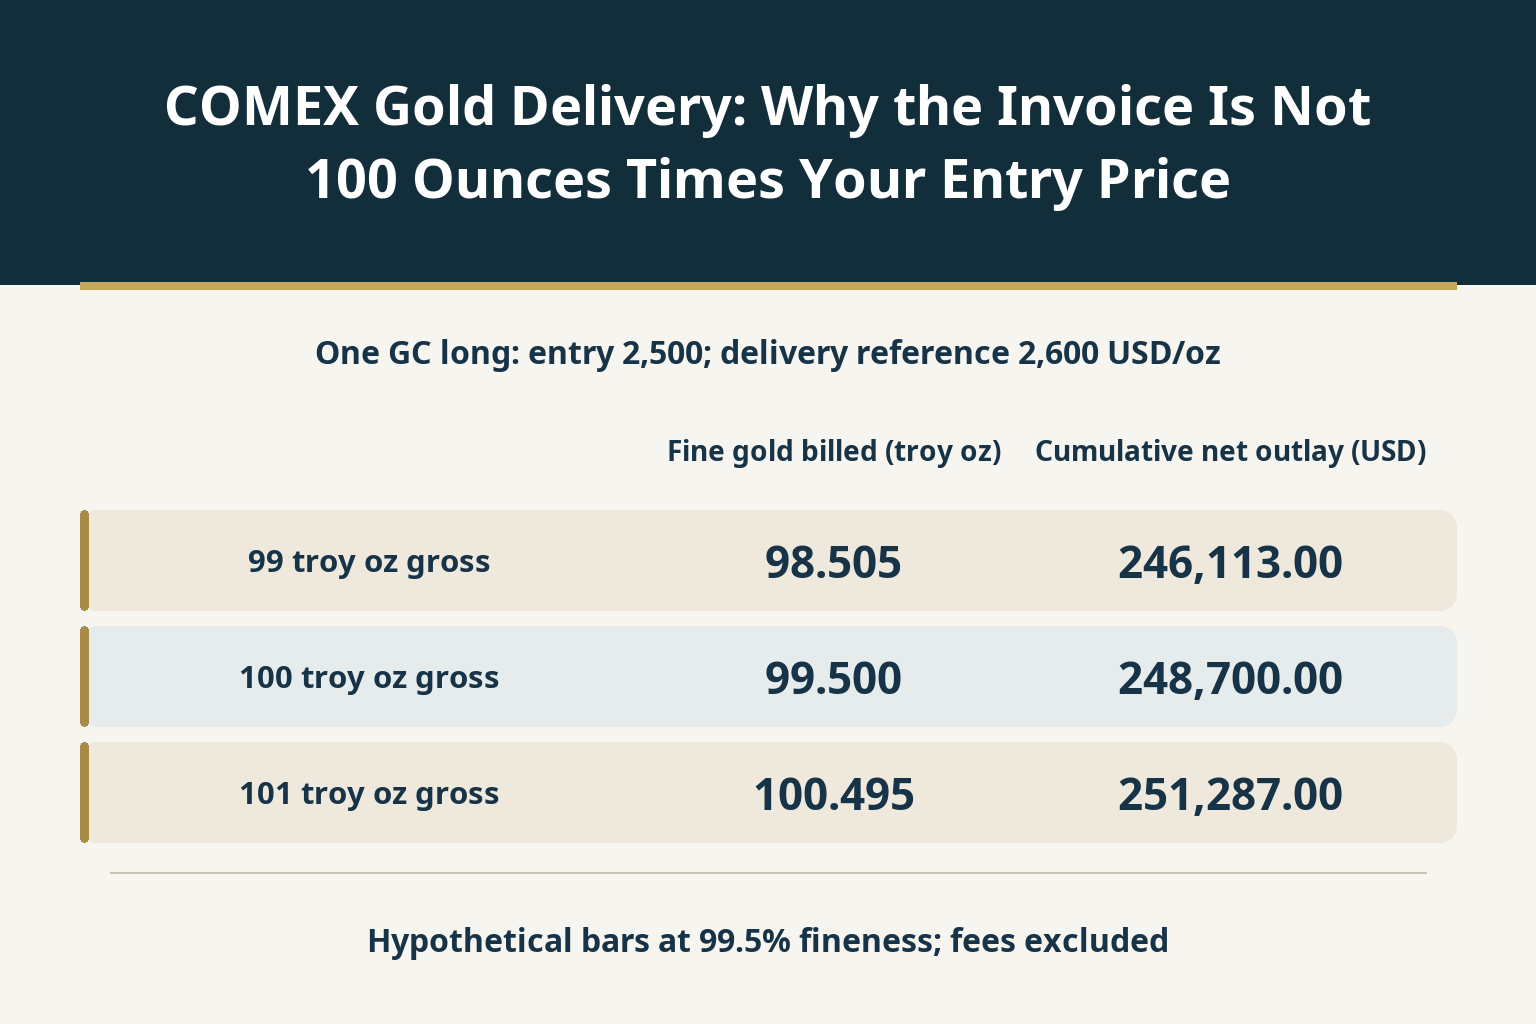
Reconcile a GC delivery invoice with fine gold weight, the applicable settlement price and cumulative futures cash flows. Three alternative bars and a falling-price example show when the original entry price does—and does not—lock the final cost.
zhan chen
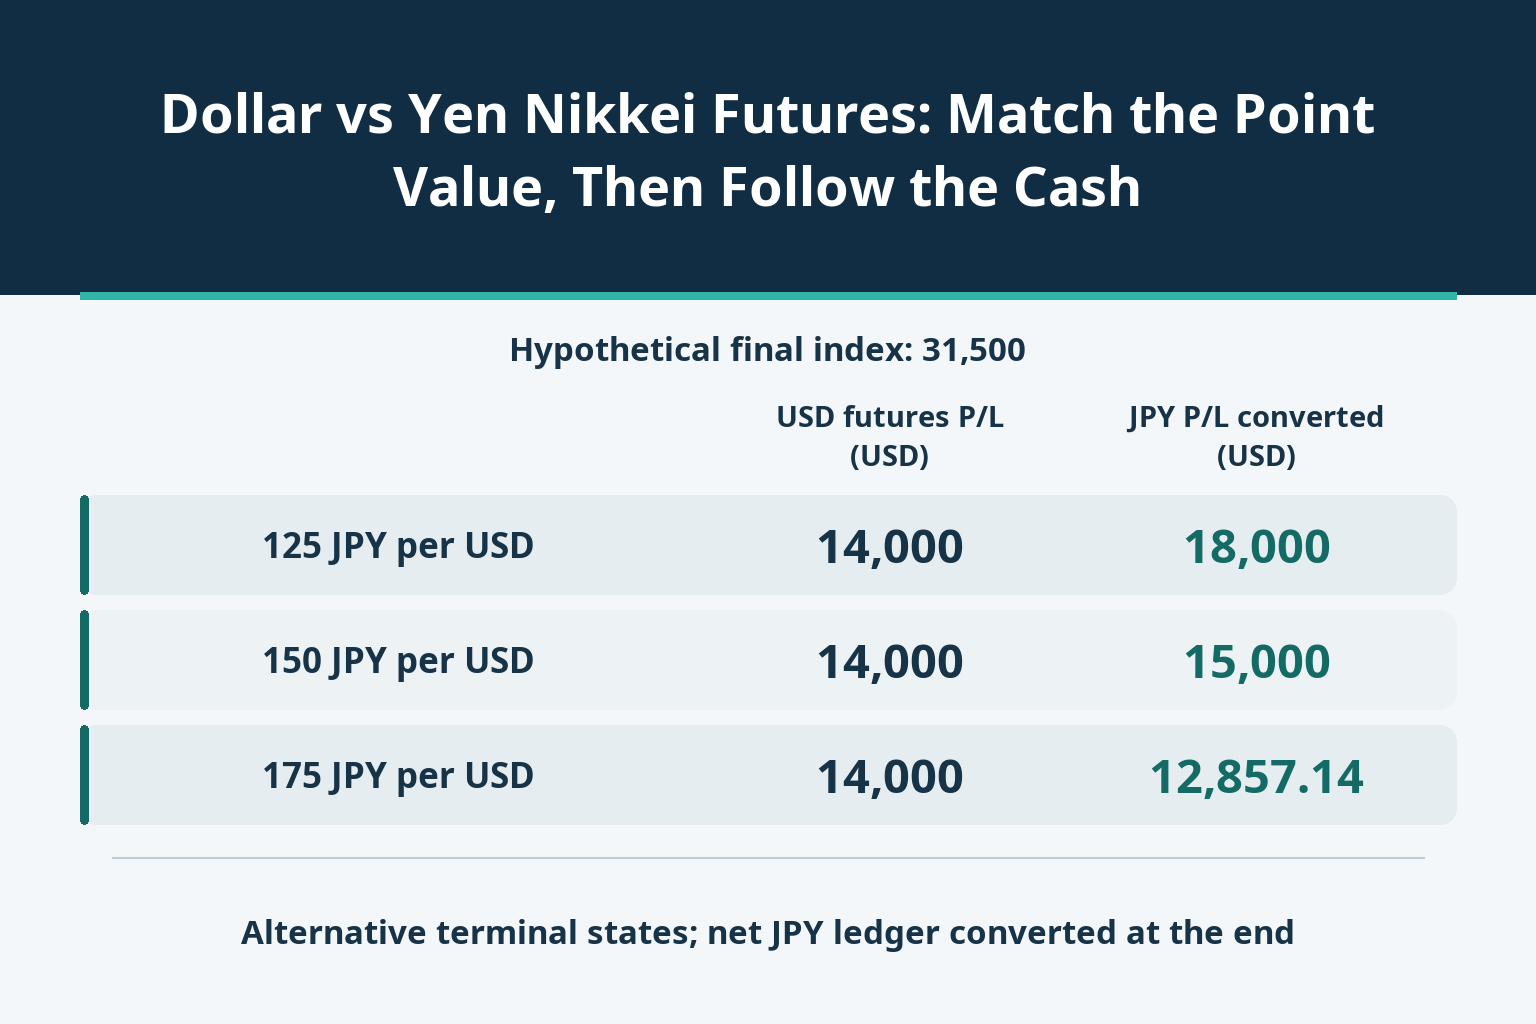
The same Nikkei settlement level does not ensure the same dollar profit. Compare properly sized USD and JPY futures, account for different entry prices, and see why converting variation cash along the way can change the result even when the index returns to its starting level.
zhan chen
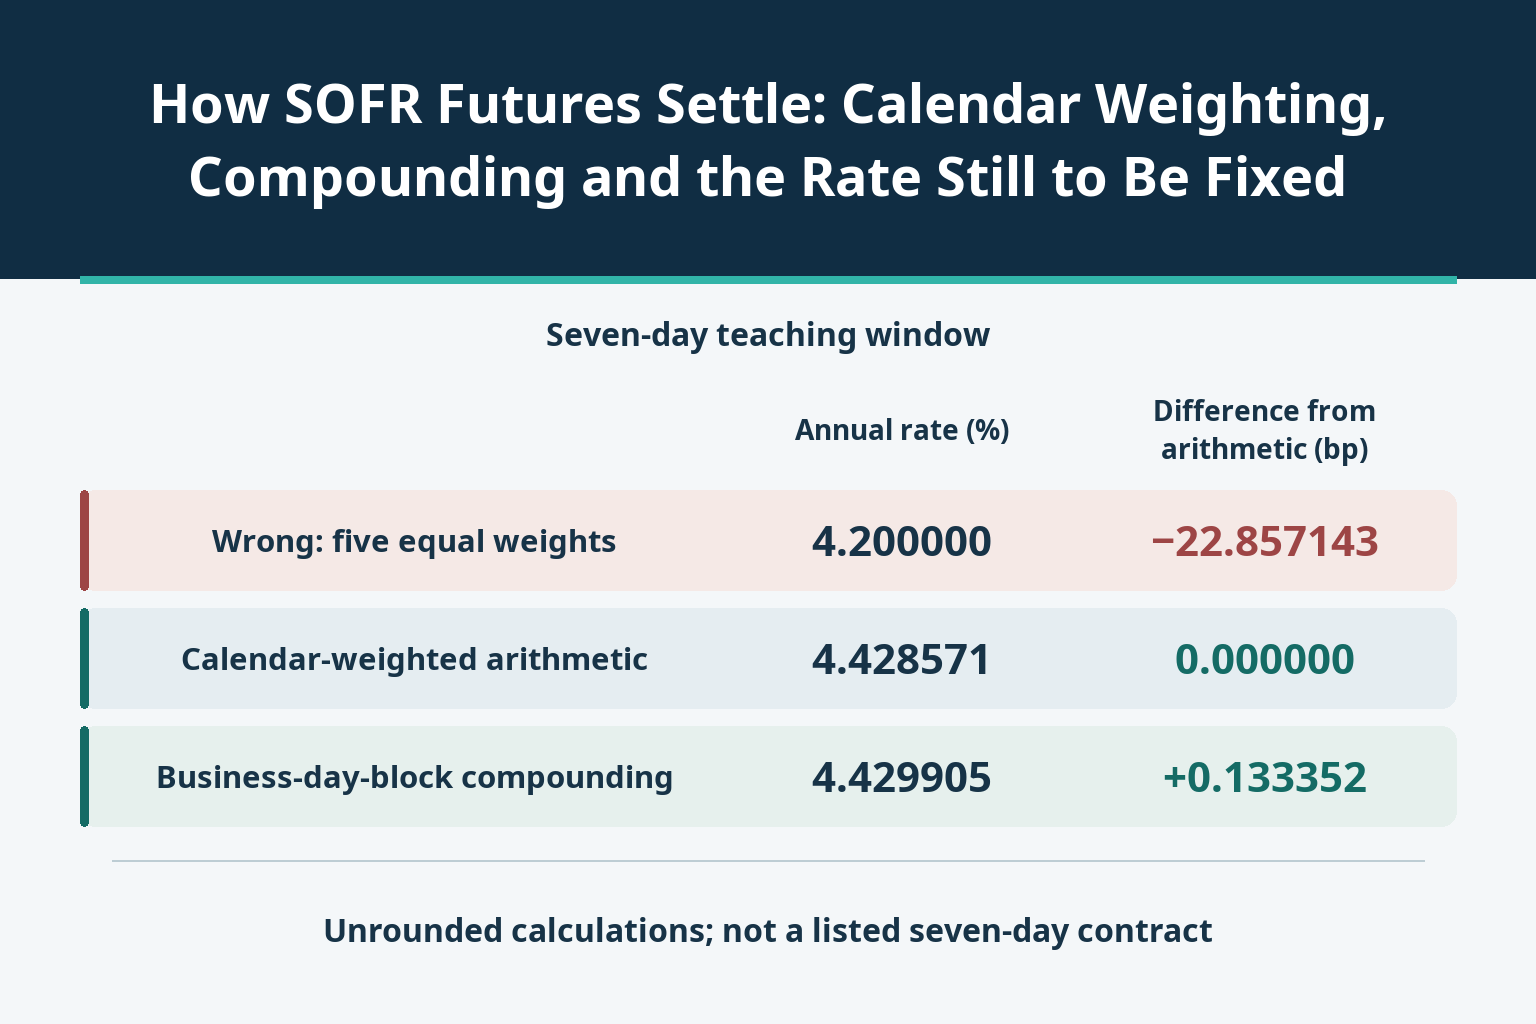
Five SOFR observations can cover seven days. Rebuild SR1 and SR3 reference rates, separate a 22.86-basis-point weighting mistake from a 0.13-basis-point compounding effect, and extract the remaining equivalent rate after part of the period has fixed.
zhan chen
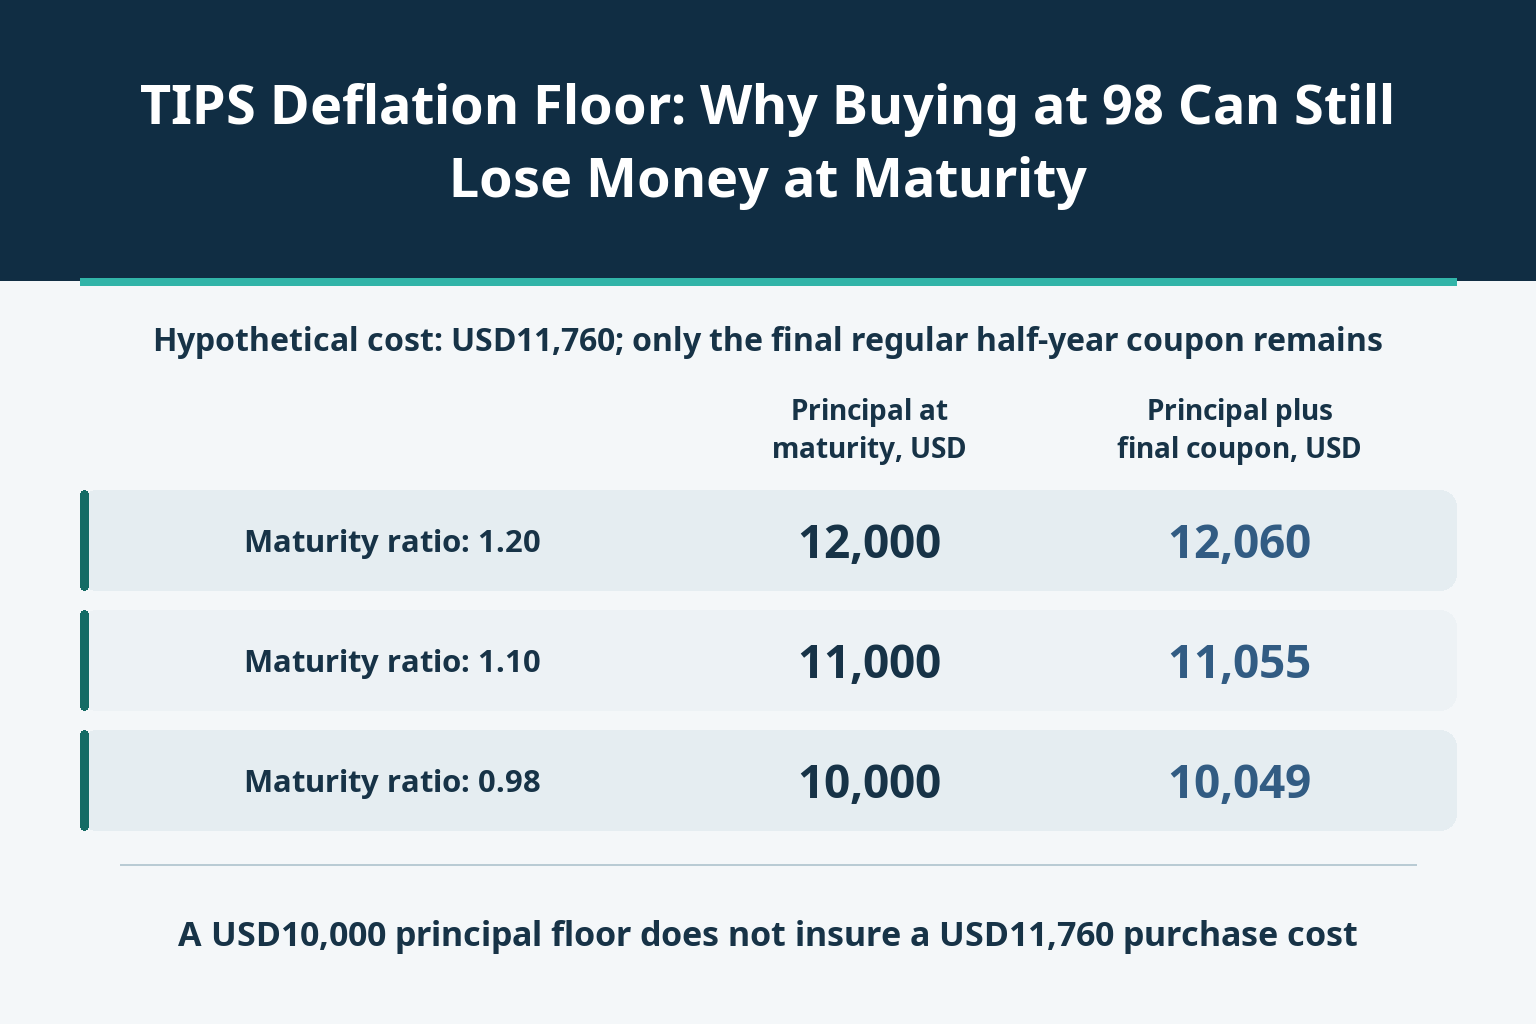
The TIPS maturity floor protects original principal, not a secondary-market buyer’s cost. A final-coupon-period example separates the floor trigger from the buyer’s cash break-even point, accounting for the index-adjusted purchase price and final coupon.
zhan chen
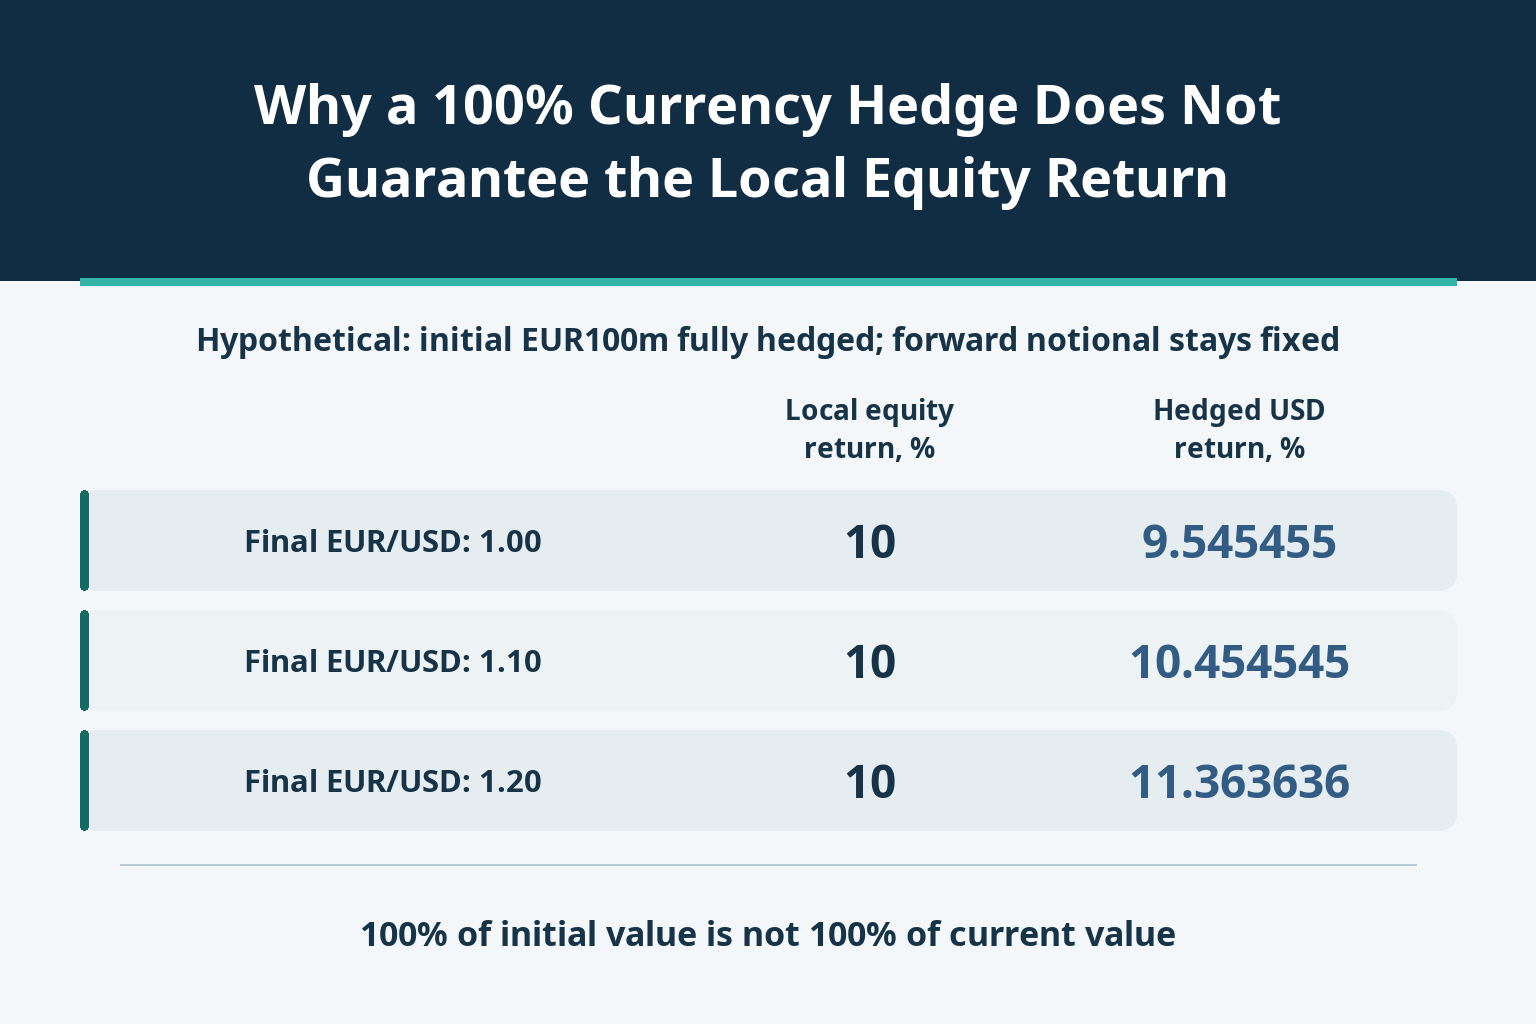
A hedge can cover all the initial foreign-currency equity value and still leave exchange-rate exposure when share prices move. A fixed-notional EUR/USD model separates forward profit, residual exposure and the effect of resetting the hedge.
zhan chen
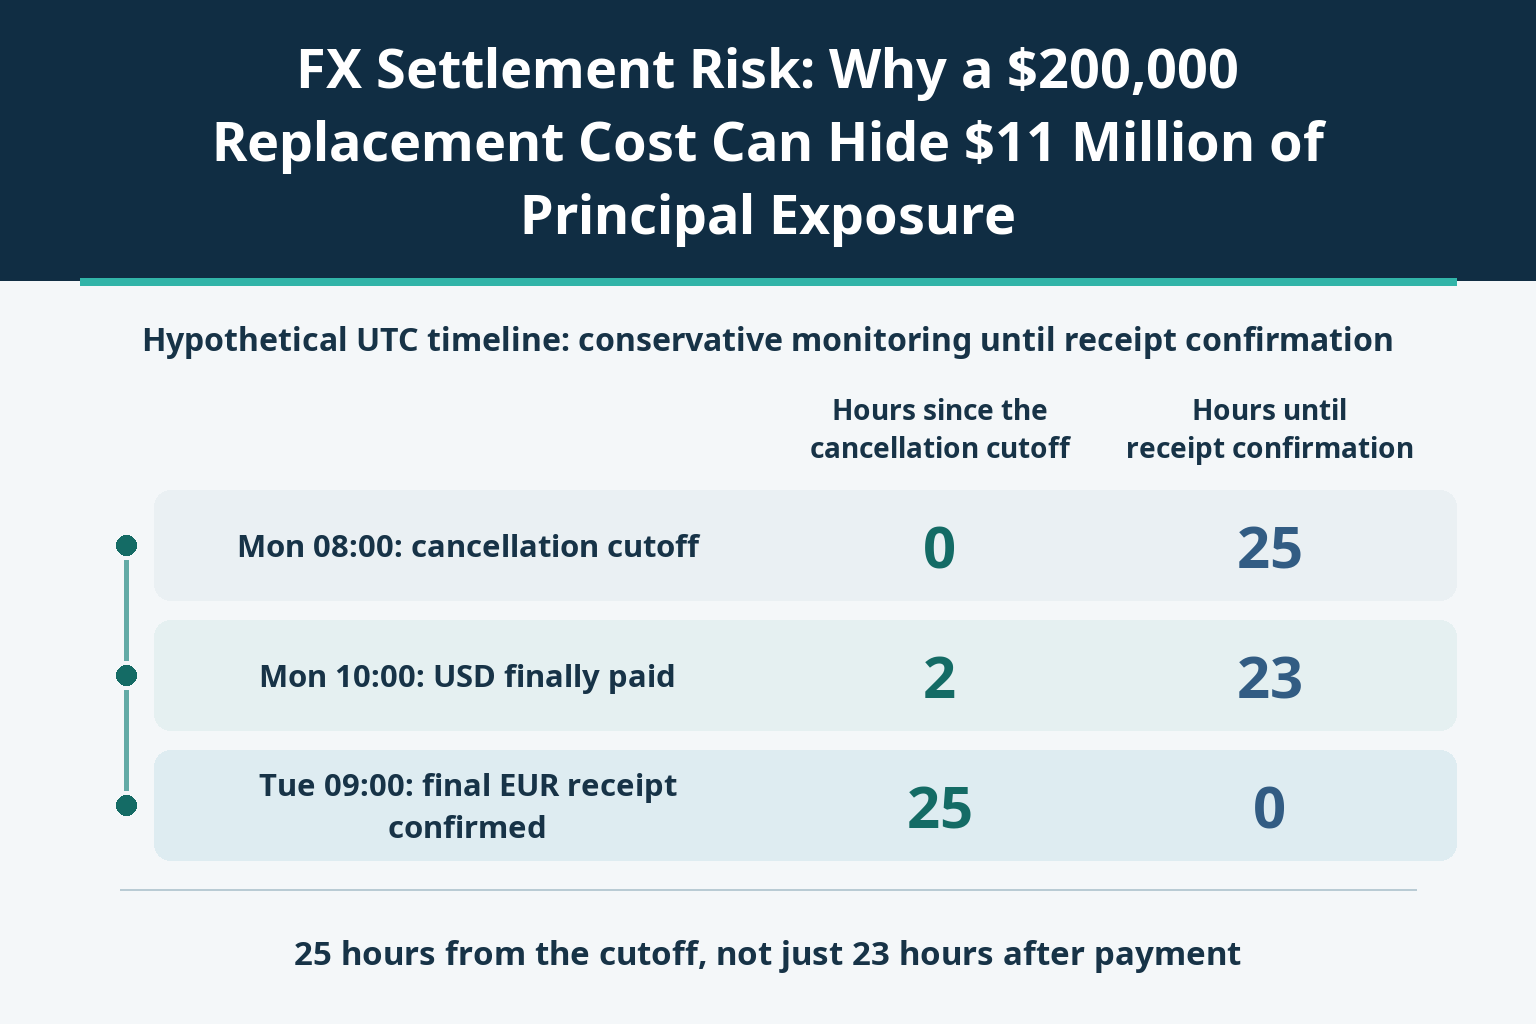
Payment versus payment protects the exchange of currency principals, not every funding need. A worked EUR/USD example separates replacement cost from principal exposure, measures a 25-hour monitoring window and shows why payment netting is not PvP.
zhan chen
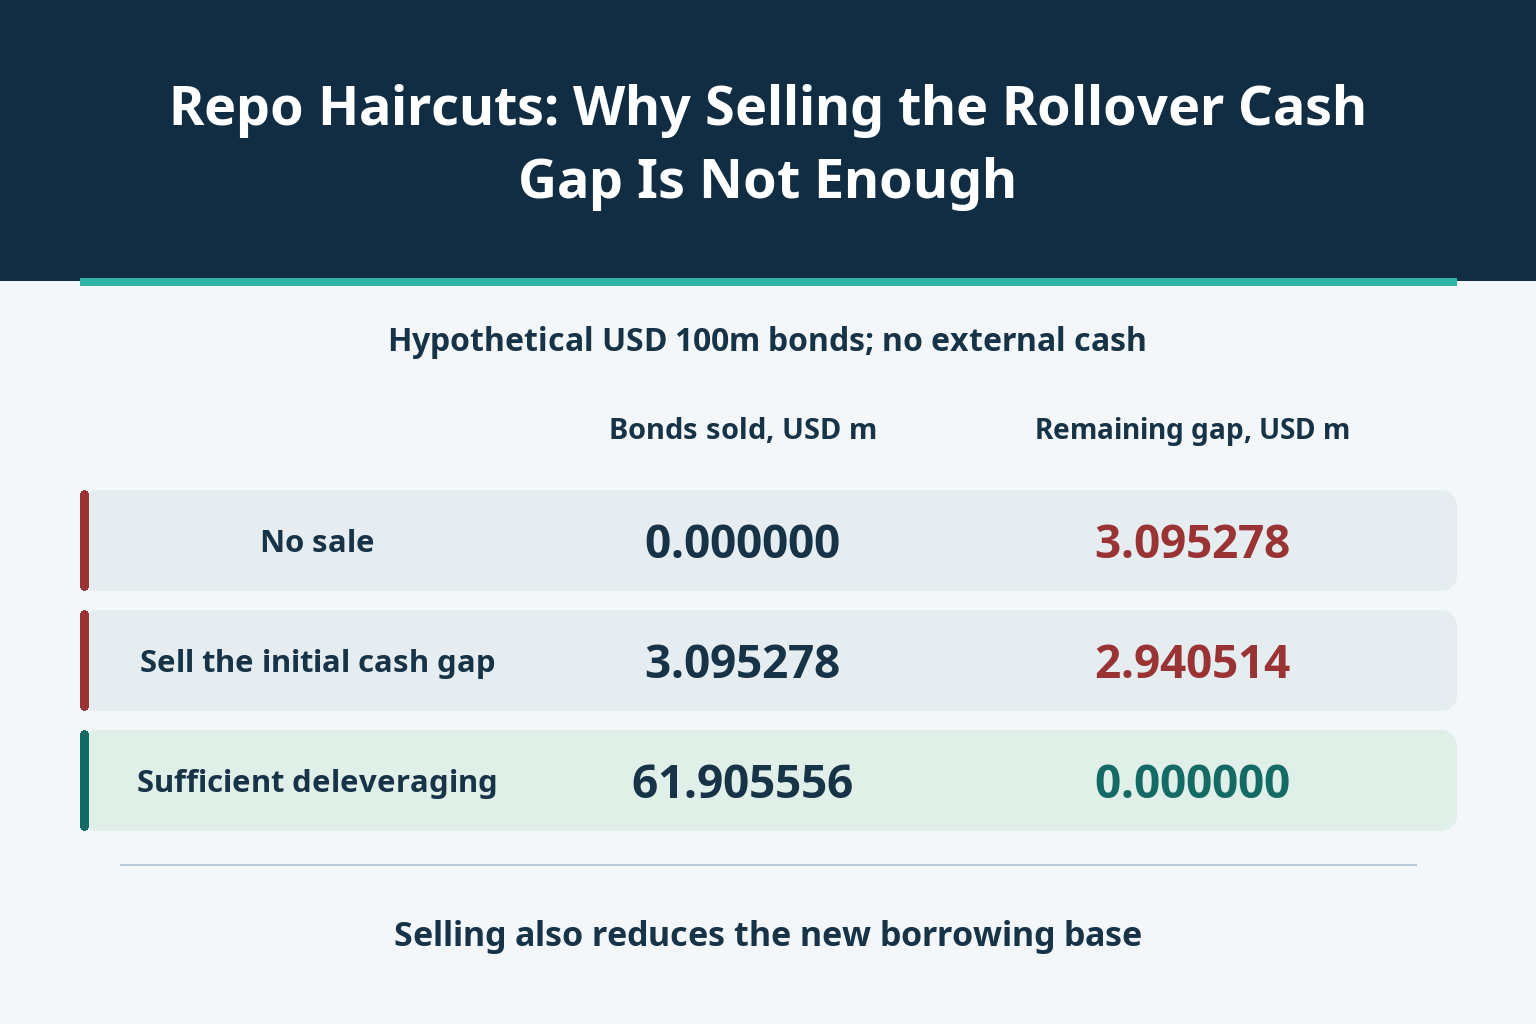
A higher haircut on a new repo can force a funding adjustment even when bond values are unchanged. An exact rollover ledger separates the cash injection, required asset sale, remaining equity and settlement constraints.
zhan chen
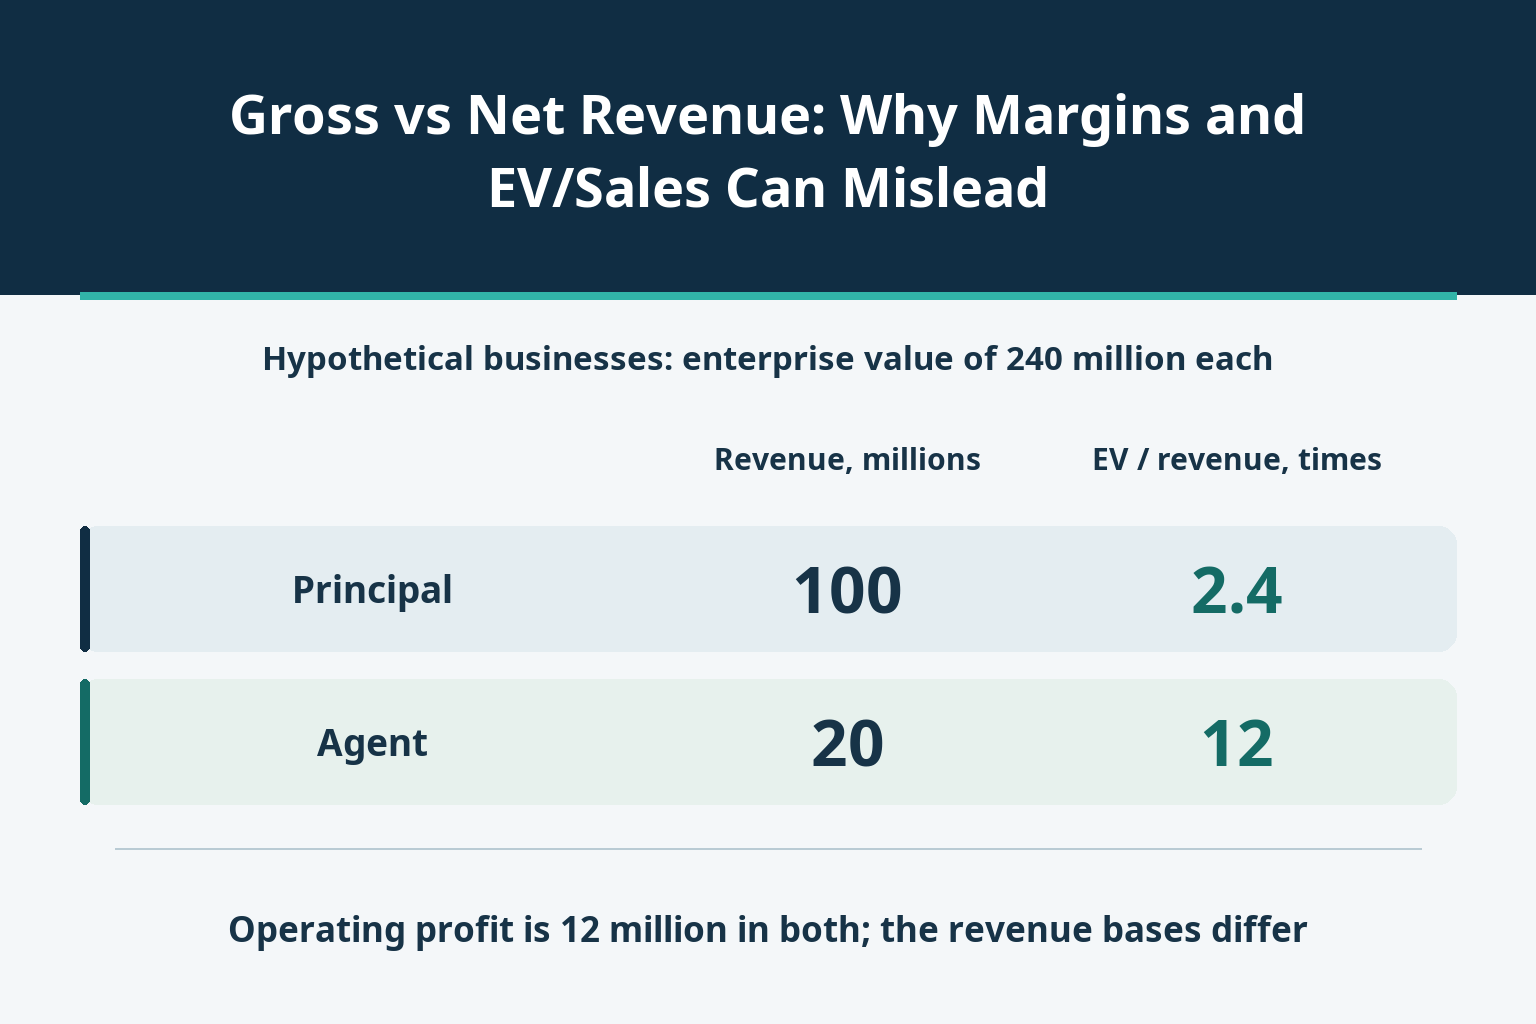
A 100% gross margin can leave the same operating profit as a 20% margin. Reconcile principal and agent revenue, test fee compression and separate changes in business mix before comparing stock valuations.
zhan chen
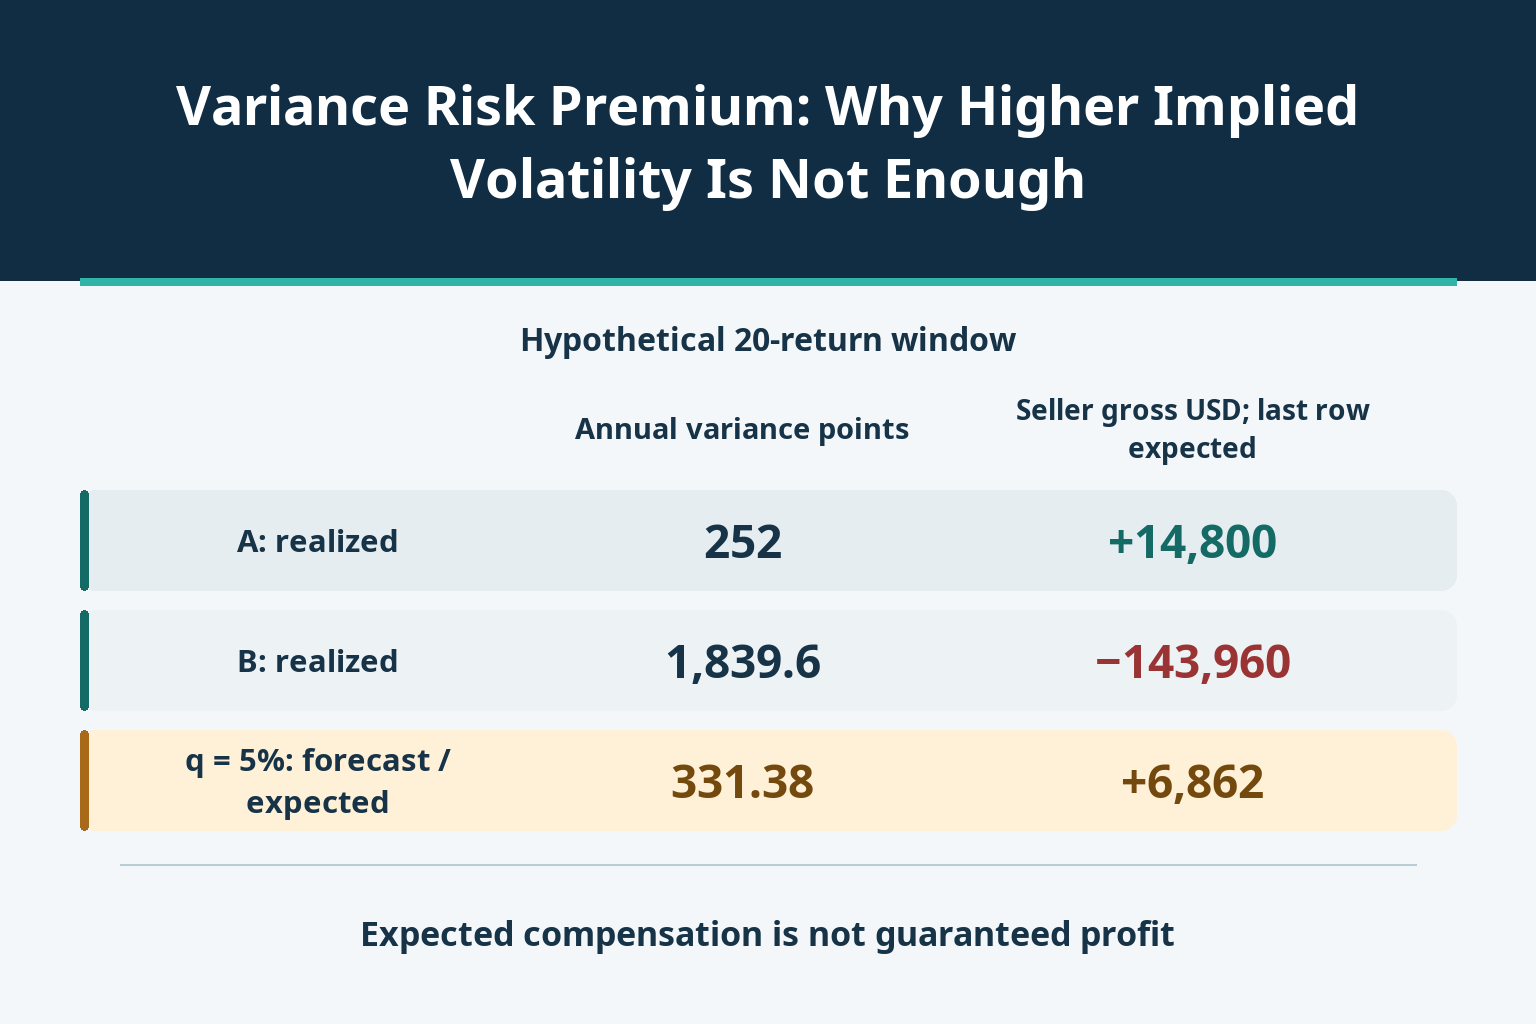
A gap between implied and historical volatility does not establish a selling edge. Two price paths and an explicit probability model show how to separate observed variance, expected compensation and the seller’s final cash result.
zhan chen

On 16 October 2026, Bitcoin has rebounded toward $82,000 after briefly falling below $80,000, but remains under pressure following a four-week low of approximately $79,770...
 Gerik
On 16 October 2026, GBP/USD has rallied sharply, reaching approximately 1.3349 and its highest level in more than three weeks as the US dollar weakened and UK economic data surprised positively...
Gerik
On 16 October, spot gold was trading around $4,175–$4,185 in different market updates, while one technical report placed resistance near $4,175.67. ...
Gerik
EUR/USD rebounds toward 1.1250 as AI investment concerns pressure US equities, Treasury yields and the Dollar. However, the Fed's restrictive policy outlook could limit the Euro's recovery.
 Warren Takunda
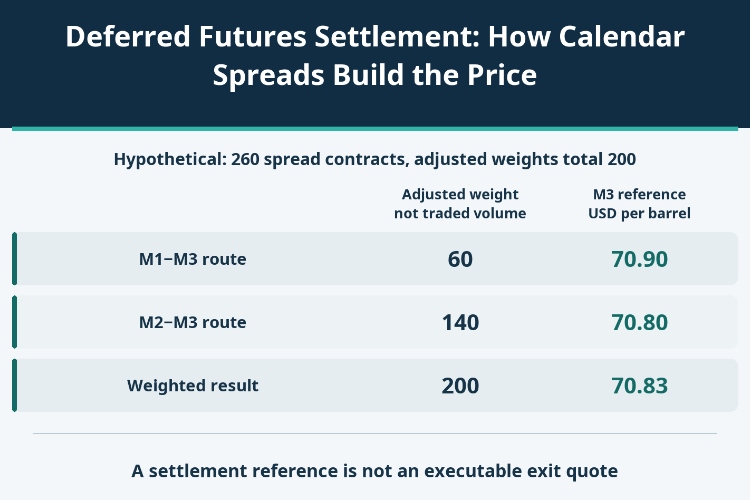
A deferred futures contract can receive a daily settlement reference without an outright trade in the settlement window. A worked crude-oil example reconstructs calendar-spread weights, distinguishes an implied range from a unique price, and tests what a ten-contract exit would actually achieve.
zhan chen
Gold/USD is currently in a low-level range-bound base-building phase. Following an earlier unilateral decline, price action has entered a consolidation process within the bottom of its trading range.
 Jason
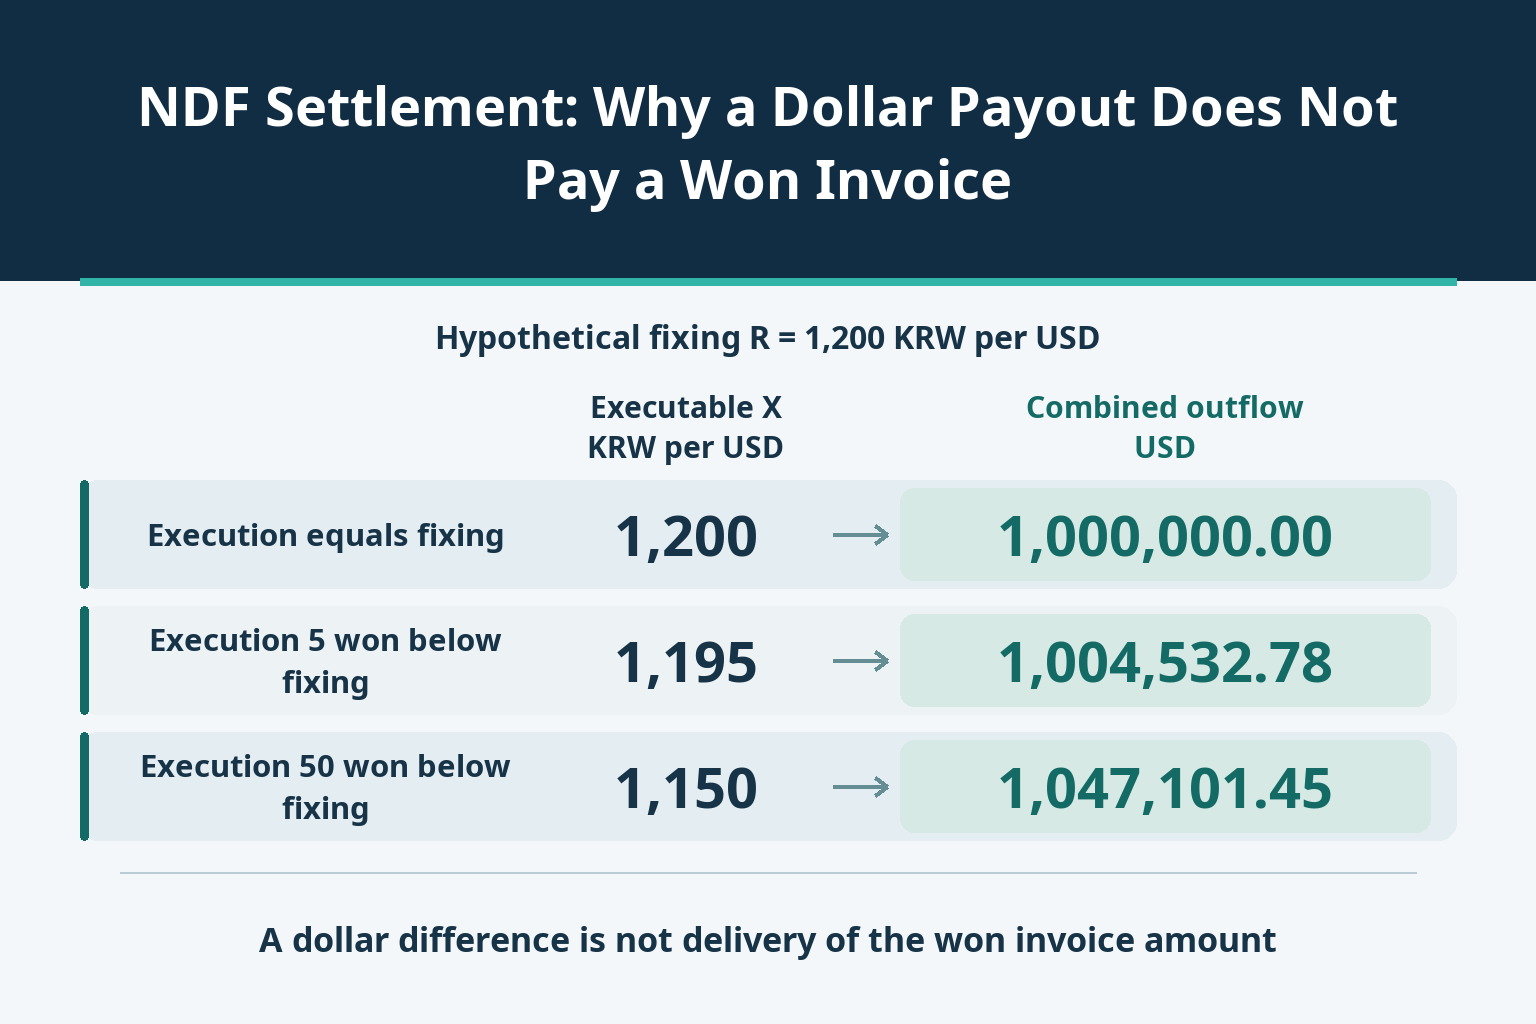
A non-deliverable forward can offset the dollar cost of a won invoice without delivering a single won. Reconcile the settlement formula with the actual currency purchase, then test the fixing, executable rate and timing of available cash to see what the hedge really covers.
zhan chen
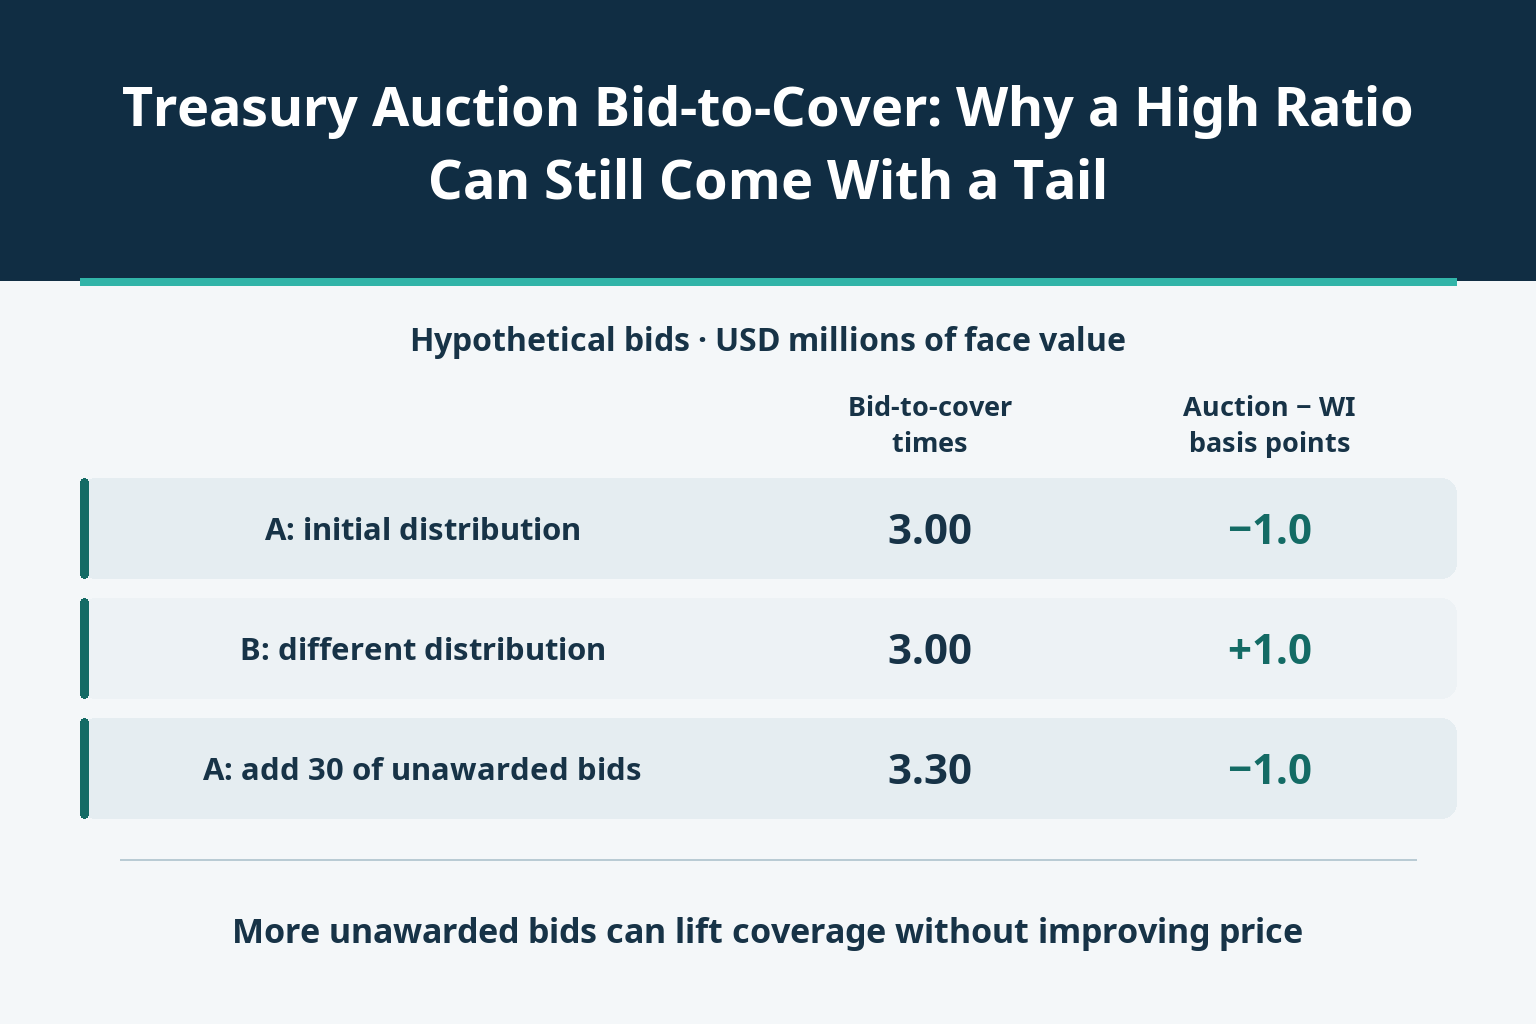
A high bid-to-cover ratio measures how much face value was bid, not how aggressively investors priced it. Two hypothetical Treasury auctions both attract three times their offering but finish on opposite sides of the same when-issued yield. Rebuild the allocations, the marginal percentage and the benchmark before calling an auction strong or weak.
zhan chen
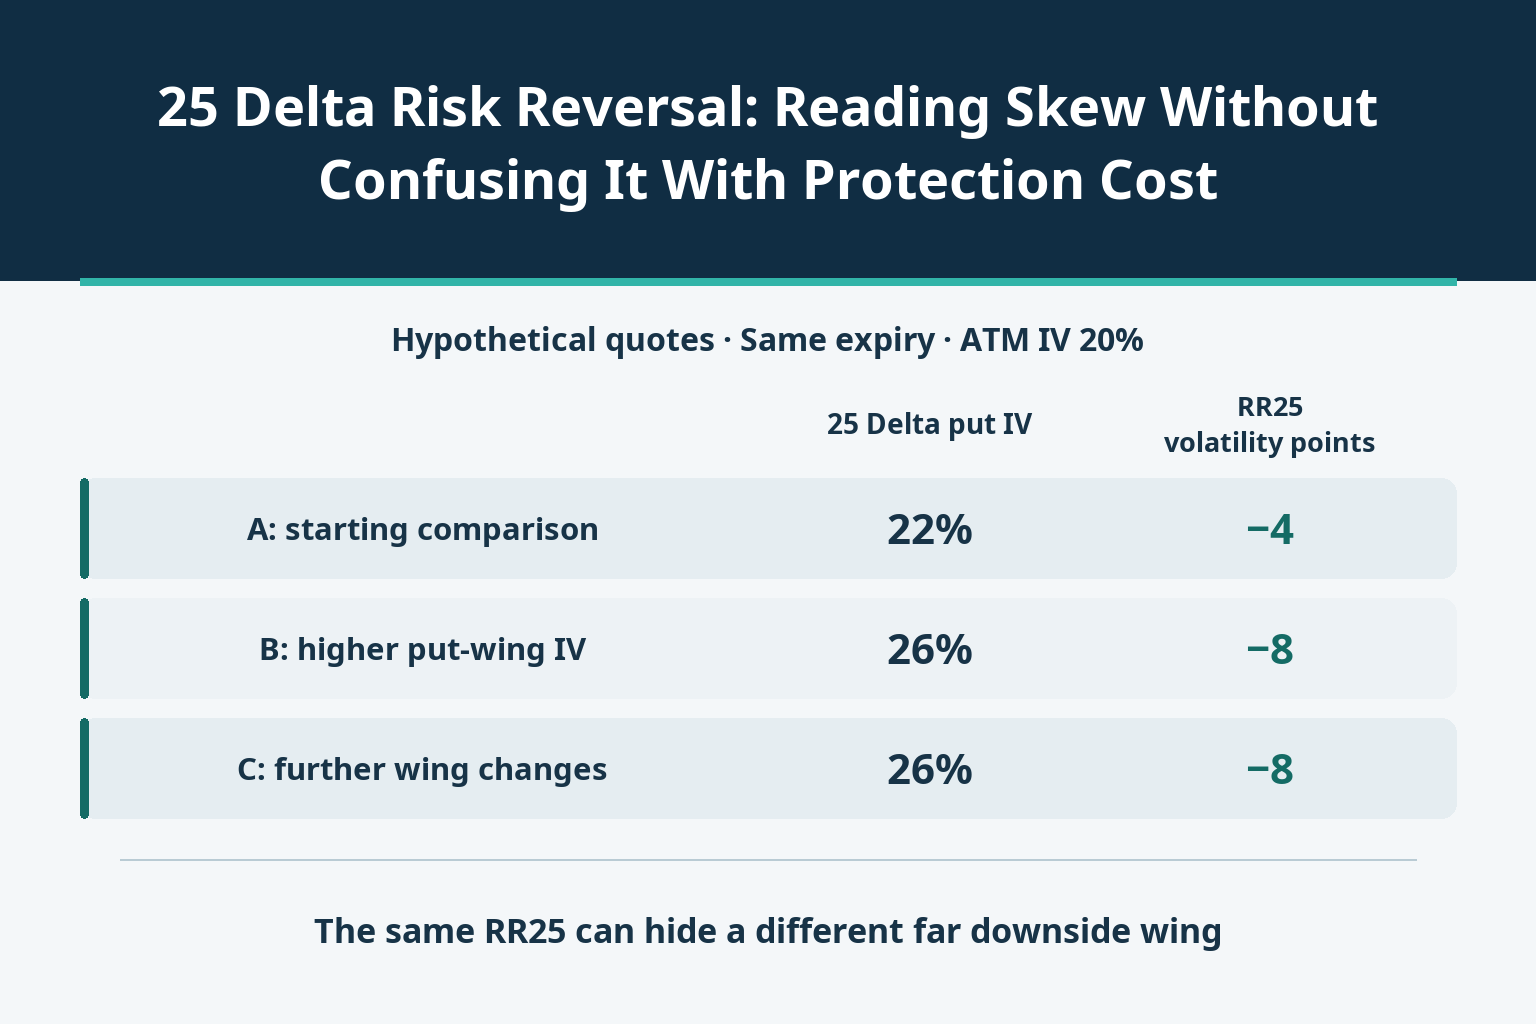
A risk reversal compares implied volatility at two Delta points. It does not price a fixed insurance contract. Three hypothetical volatility snapshots and a fixed-strike experiment show how unchanged at-the-money volatility can conceal a different downside wing—and why the strike matters.
zhan chen
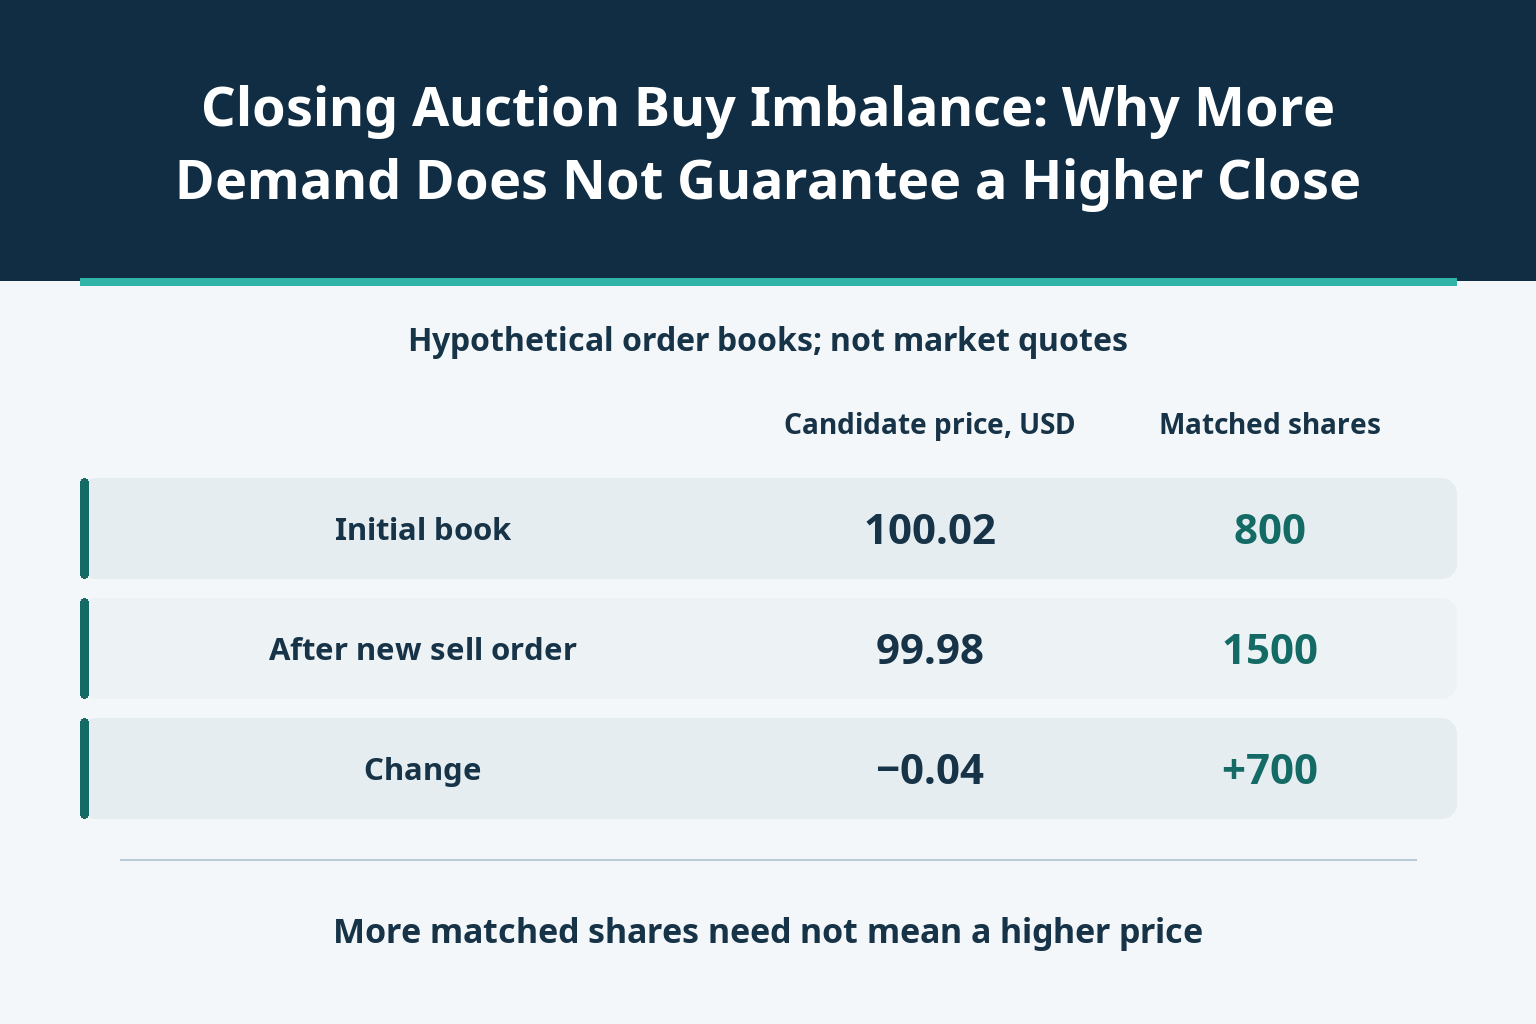
Rebuild two hypothetical limit-order books to see how a buy surplus becomes a sell surplus, why matched volume can rise as the candidate price falls, and which venue, timing and execution checks matter.
zhan chen


